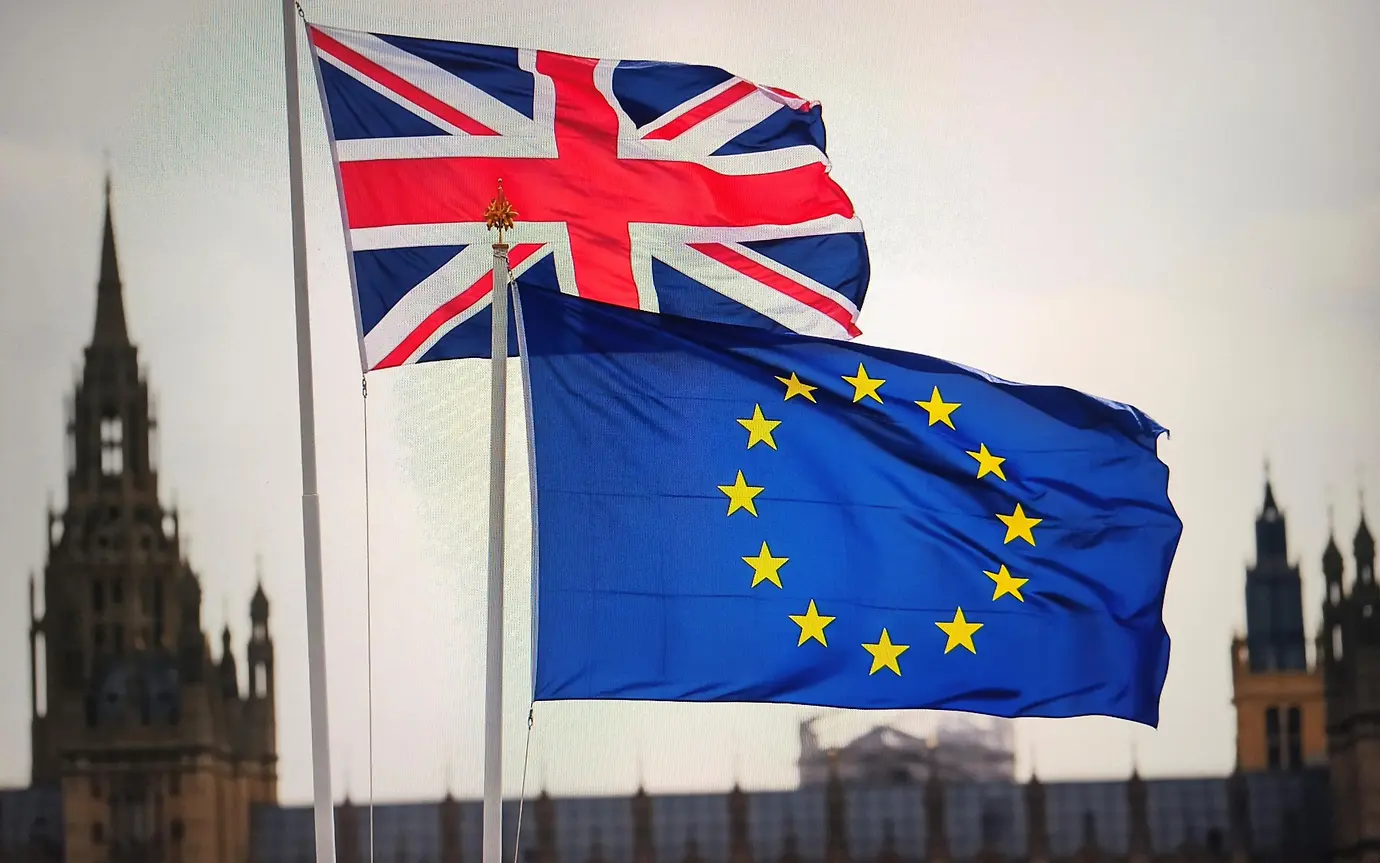
As all eyes have been on Downing Street this week, it has also marked 10 years since the UK voted to leave the European Union, providing a natural moment to reflect on a decade of political and economic change.
Brexit remains a divisive topic, posing significant challenges for successive governments and contributing to the UK’s frequent leadership changes over the past decade.
During this period, investors have had to navigate shifting fiscal priorities amid leadership changes and new trade relationships. For investors, this has often pushed risk premiums on UK assets higher, contributed to elevated government borrowing costs, and led to periods of sterling volatility.
While much attention has focused on the costs associated with higher trade barriers and political uncertainty, the UK has also gained greater regulatory autonomy, enabling it to move independently in sectors such as financial services, life sciences and artificial intelligence. Harnessed effectively, these freedoms could attract investment and enhance the UK’s long-term growth potential.
Against this backdrop, this week we look at how Brexit has unfolded 10 years on, how it has impacted the economy, and how a government under Andy Burnham could navigate the path ahead, as he appears to be on an uncontested track to the Labour leadership.
Leaving the EU has weighed on the UK economy over the past decade. According to estimates from the Office for Budget Responsibility, Brexit has reduced UK GDP by roughly 4% compared with a scenario in which the UK remained in the EU. However, other factors have also weighed on the UK’s growth potential since 2010, including low savings rates, the after-effects of the global financial crisis, weak manufacturing productivity, and regional economic concentration.1 Leaving the EU has also lowered employment and pushed prices higher, according to Deutsche Bank research.
Leaving the EU also increased administrative burdens and barriers to trade in the UK. From an economic perspective, trade frictions often raise costs for businesses, particularly those reliant on complex international supply chains. While the UK retained tariff-free access to EU markets under the Trade and Cooperation Agreement, businesses have faced additional costs from customs declarations, regulatory checks and rules-of-origin requirements. Research suggests these barriers have reduced UK-EU goods trade and increased costs for importers and exporters, with some studies showing that a portion of these higher costs has been passed on to consumers over time.2
Some economists believe these frictions have contributed to the UK’s relatively persistent inflation pressures in recent years by increasing import costs.3
However, not all negative forecasts about Brexit came to fruition. Supporters say that leaving the EU has given the UK greater flexibility over regulation and trade policy across a variety of sectors, such as financial services, allowing London to maintain its position as a leading global centre for derivatives trading and a global financial hub.
In addition, predictions that a significant number of financial services jobs could move to Europe due to Brexit never materialised. In 2017, the year after the UK voted to leave, 1.1 million people worked in finance; today that number is the same.4 London is still the capital of cross-border finance in key areas, and as a trading venue for currencies, insurance and derivatives, it is unmatched.5
Exports of professional services, technology, telecommunications, consulting and financial services have continued to expand, particularly to both the US and Europe. This is crucial, as goods trade has generally been weaker. Financial services contributed £224 billion to the economy in 2025, or about 8% of GDP, while Britain’s net exports of these services total £93 billion a year, more than those of any other country.6
The UK has also sought to establish itself as a more innovation-friendly jurisdiction in areas such as artificial intelligence and life sciences, where policymakers argue that a lighter-touch regulatory approach could support investment and long-term competitiveness. The government's AI Opportunities Action Plan and the creation of AI Growth Zones are intended to accelerate investment by reducing barriers to the development of data centres, computing capacity and related infrastructure.7
However, tapping this potential would require the UK to fast-track planning permissions to develop the necessary infrastructure for the industries of the future. It is these high-growth, technology-driven sectors such as AI and digital infrastructure that are expected to drive foreign investment, rather than projects such as Heathrow expansion or proposals for the nationalisation of public utilities.
Investors will closely watch to see whether a potential Burnham government would follow Starmer’s lead in seeking closer ties with the EU. While the UK has signed more than 70 trade agreements since leaving the EU and joined the CPTPP (Comprehensive and Progressive Agreement for Trans-Pacific Partnership) trading bloc, the economic benefits have so far been modest.
In the past, Burnham has been critical of the economic impact of Brexit, and has generally favoured a pragmatic approach focused on rebuilding cooperation with Europe rather than revisiting the question of EU membership.
A Burnham government may place greater emphasis on regional investment, transport infrastructure and devolution, particularly as his roots are in northern England. For investors, the success of such investments will depend on whether they can improve productivity, attract private capital and narrow regional disparities in economic performance.8
The 10-year anniversary of Brexit offers a useful reminder that the economic legacy of this decision is still unfolding. The challenge for the next government will be to steer the economy towards growth opportunities and attract investment. Investors in the UK continue to demand a premium due to the political and economic risks, which keeps borrowing costs elevated. If the government can steer policy in the right direction, it would help unlock the UK’s potential.
[1] Deutsche Bank
[2] Deutsche Bank
[3] Deutsche Bank
[4] How to capitalise on London’s thriving financial industry
[5] Has the City of London finally got its mojo back?
[6] How to capitalise on London’s thriving financial industry
[7] AI Opportunities Action Plan - GOV.UK
[8] Deutsche Bank
LGT Wealth Management UK LLP is authorised and regulated by the Financial Conduct Authority Registered in England and Wales: OC329392. Registered office: 14 Cornhill, London, EC3V 3NR. LGT Wealth Management Limited is authorised and regulated by the Financial Conduct Authority. Registered in Scotland number SC317950 at Capital Square, 58 Morrison Street, Edinburgh, EH3 8BP. LGT Wealth Management Jersey Limited is incorporated in Jersey and is regulated by the Jersey Financial Services Commission in the conduct of Investment Business and Funds Service Business: 102243. Registered office: Sir Walter Raleigh House, 48-50 Esplanade, St Helier, Jersey JE2 3QB. LGT Wealth Management (CI) Limited is registered in Jersey and is regulated by the Jersey Financial Services Commission: 5769. Registered Office: at Sir Walter Raleigh House, 48 – 50 Esplanade, St Helier, Jersey JE2 3QB. LGT Wealth Management US Limited is authorised and regulated by the Financial Conduct Authority and is a Registered Investment Adviser with the US Securities & Exchange Commission (“SEC”). Registered in England and Wales: 06455240. Registered Office: 14 Cornhill, London, EC3V 3NR.
This communication is provided for information purposes only. The information presented is not intended and should not be construed as an offer, solicitation, recommendation or advice to buy and/or sell any specific investments or participate in any investment (or other) strategy and should not be construed as such. The views expressed in this publication do not necessarily reflect the views of LGT Wealth Management US Limited as a whole or any part thereof. Although the information is based on data which LGT Wealth Management US Limited considers reliable, no representation or warranty (express or otherwise) is given as to the accuracy or completeness of the information contained in this Publication, and LGT Wealth Management US Limited and its employees accept no liability for the consequences of acting upon the information contained herein. Information about potential tax benefits is based on our understanding of current tax law and practice and may be subject to change. The tax treatment depends on the individual circumstances of each individual and may be subject to change in the future.
All investments involve risk and may lose value. Your capital is always at risk. Any investor should be aware that past performance is not an indication of future performance, and that the value of investments and the income derived from them may fluctuate, and they may not receive back the amount they originally invested.