As the football world focuses on managers selecting their best eleven players for the World Cup, investors are scrutinising a different team sheet: the members of the Federal Open Market Committee (FOMC) and its new chairman, Kevin Warsh. Like any World Cup squad, the committee contains players with different strengths and styles. Some members favour a more aggressive approach to tackling inflation, while others prefer looser economic conditions.
Central bankers are now weighing whether they need to tackle inflation. For much of the past five years, policymakers underestimated how persistent inflation would prove after the pandemic. Having been caught out before, policymakers are determined not to make the same mistake again.
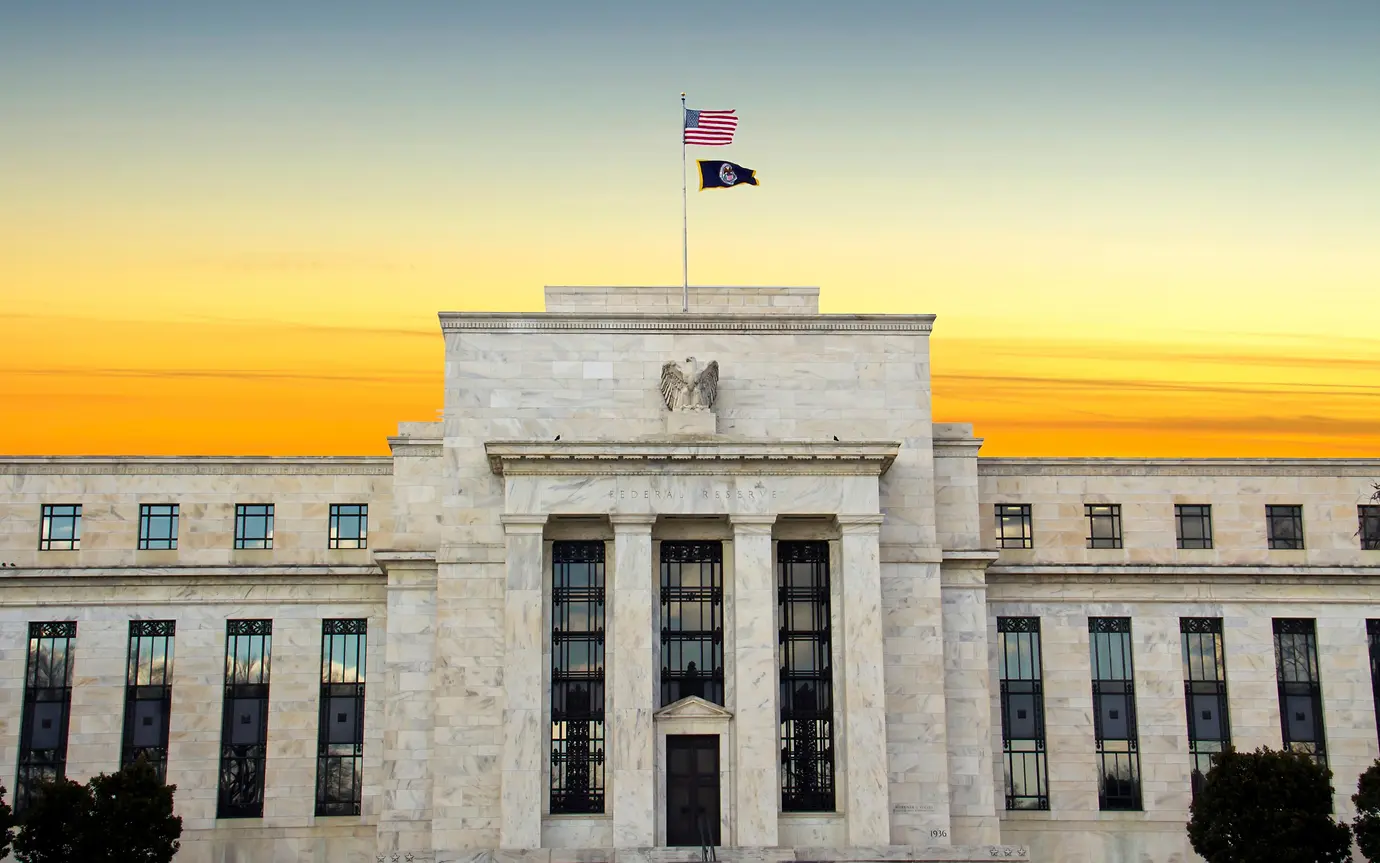
That mindset was evident at this week's Federal Reserve (Fed) meeting. While the Fed left interest rates unchanged, the tone of policymakers was noticeably more hawkish than many investors had anticipated.1
At first glance, it may seem surprising that the Fed is more cautious, given recent progress towards a ceasefire in the Middle East and the prospect of lower energy prices as supply disruptions ease. However, it is worth stepping back from recent developments to assess the broader picture. If the conflict had never happened, the Fed would be confronting an economy that has been showing signs of strength.
Recent US labour market data has shown signs of stabilisation. This matters as the Fed has a dual mandate to focus on maximum employment and stable prices. Concerns about the labour market led officials to cut interest rates three times last year. The improvement in recent months, paired with solid consumer spending amid the fiscal support from the so-called “big, beautiful bill”, has drawn increased attention from policymakers. At the same time, the extraordinary wave of investment linked to artificial intelligence (AI) is creating fresh demand for energy, power infrastructure and industrial resources, improving employment prospects for workers in those industries. While AI may ultimately boost productivity and weigh on employment, the investment boom is currently contributing to near-term price pressures across parts of the economy.
Against that backdrop, the Fed's more hawkish stance is understandable. With geopolitical tensions beginning to ease, officials are increasingly able to focus on the underlying strength of the domestic economy. In other words, inflationary pressures are now arising from more robust domestic demand, rather than external factors.
The latest dot plot – which shows where individual Fed policymakers expect interest rates to be in coming years – reflected this shift outlined above. Roughly half of policymakers now expect at least one additional rate increase before year-end.2 Notably, Chair Warsh abstained from providing his view, given his prior critique of central banks over-communicating. The Fed also removed language from its statement on 17 June that had previously outlined conditions for future rate cuts, cementing the shift in stance.3
Elsewhere, central banks have opted to navigate conditions in their own ways. The European Central Bank (ECB) and the Bank of Japan (BoJ) each raised rates by 0.25% in their recent meetings as their strategy is to focus on inflation. Being on the back foot, they opted to respond now. The Bank of England (BoE) meanwhile chose to keep rates unchanged for now, helped by softer-than-expected inflation data and lower energy prices. The growth picture remains challenging for the UK, with the Labour Party’s in-fighting causing further uncertainty.
The easing of tensions in the Middle East helps central banks narrow their forecasts. Lower energy prices and the reopening of key trade routes reduce the risk of another supply-driven inflation shock and give policymakers more room to focus on domestic conditions.
For investors, that marks an important shift. Earlier in the year, the main question was whether the closure of the Strait of Hormuz and its knock-on effects would force central banks to hike rates and keep policy tighter for longer. Today, attention has shifted to domestic conditions as economic differences are driving a larger divergence between the major central banks. For the US, the debate is increasingly about whether strong labour markets, supportive fiscal policy and AI-driven investment are likely to keep inflation elevated beyond the point of comfort, which could drive rate increases even as external shocks fade. Ultimately, policymakers must navigate a difficult balance between growth and inflation.
While central banks were united in facing the threat of inflation in 2022, this time around they are adopting their own strategies. As the US and Iran sign a deal to end the conflict, focus is now shifting to domestic economic conditions rather than external supply shocks. It is worth remembering that if the US does move to raise interest rates in coming quarters, it likely means the economy is doing better than expected. In that context, tighter policy should be seen as a response to economic strength, rather than a cause for concern.
[1] Fed Holds Rates and Leans Toward Fighting Inflation With Future Increases - The New York Times
[2] Summary of Economic Projections, June 17, 2026
[3] Fed Holds Rates and Leans Toward Fighting Inflation With Future Increases - The New York Times
LGT Wealth Management UK LLP is authorised and regulated by the Financial Conduct Authority Registered in England and Wales: OC329392. Registered office: 14 Cornhill, London, EC3V 3NR. LGT Wealth Management Limited is authorised and regulated by the Financial Conduct Authority. Registered in Scotland number SC317950 at Capital Square, 58 Morrison Street, Edinburgh, EH3 8BP. LGT Wealth Management Jersey Limited is incorporated in Jersey and is regulated by the Jersey Financial Services Commission in the conduct of Investment Business and Funds Service Business: 102243. Registered office: Sir Walter Raleigh House, 48-50 Esplanade, St Helier, Jersey JE2 3QB. LGT Wealth Management (CI) Limited is registered in Jersey and is regulated by the Jersey Financial Services Commission: 5769. Registered Office: at Sir Walter Raleigh House, 48 – 50 Esplanade, St Helier, Jersey JE2 3QB. LGT Wealth Management US Limited is authorised and regulated by the Financial Conduct Authority and is a Registered Investment Adviser with the US Securities & Exchange Commission (“SEC”). Registered in England and Wales: 06455240. Registered Office: 14 Cornhill, London, EC3V 3NR.
This communication is provided for information purposes only. The information presented is not intended and should not be construed as an offer, solicitation, recommendation or advice to buy and/or sell any specific investments or participate in any investment (or other) strategy and should not be construed as such. The views expressed in this publication do not necessarily reflect the views of LGT Wealth Management US Limited as a whole or any part thereof. Although the information is based on data which LGT Wealth Management US Limited considers reliable, no representation or warranty (express or otherwise) is given as to the accuracy or completeness of the information contained in this Publication, and LGT Wealth Management US Limited and its employees accept no liability for the consequences of acting upon the information contained herein. Information about potential tax benefits is based on our understanding of current tax law and practice and may be subject to change. The tax treatment depends on the individual circumstances of each individual and may be subject to change in the future.
All investments involve risk and may lose value. Your capital is always at risk. Any investor should be aware that past performance is not an indication of future performance, and that the value of investments and the income derived from them may fluctuate, and they may not receive back the amount they originally invested.