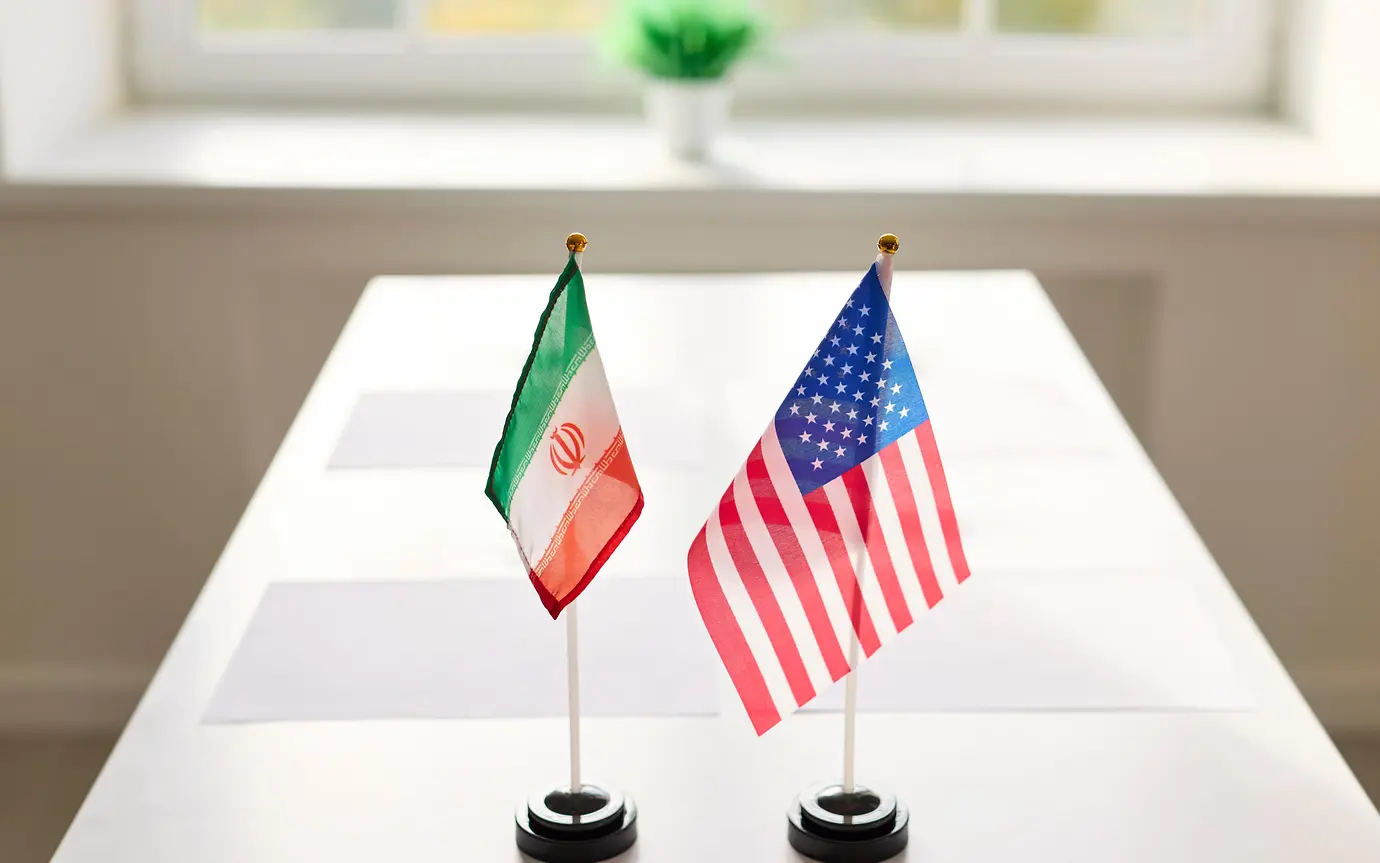
Global markets have staged a relief rally following this week’s ceasefire between the United States and Iran, although attention will soon shift to whether the calm will hold. The 7 April agreement, reached after a period of heightened tensions over the Strait of Hormuz, has temporarily reduced the risk of a broader regional conflict – and with it, the threat of sustained disruption to global oil and natural gas supplies. Investors are now weighing how long the truce may last and what it means for energy markets, inflation and geopolitical risks.
Under the two-week ceasefire, Iran says safe passage through the Strait of Hormuz will resume. This sparked a sharp fall in oil prices and the dollar, while equities, bonds and gold moved higher. President Donald Trump claimed the US had achieved its military objectives and described Iran’s 10-point proposal as a “workable basis” for negotiation. Tehran signalled conditional acceptance, while Pakistan’s Prime Minister Shehbaz Sharif has offered to host talks in Islamabad on 10 April aimed at securing a peace deal.
Brent crude fell sharply in the immediate aftermath of the 7 April ceasefire, dropping 13.5% to $94 a barrel in early trading on 8 April. Prices had traded above $110 a barrel at the height of tensions before retreating as reports of Pakistan’s mediation efforts emerged, briefly touching $91 a barrel once the ceasefire was confirmed. By the end of the week, Brent was trading at around $98 a barrel, suggesting that while the geopolitical risk premium has eased, it has not fully dissipated.1
Global equities responded with a relief rally, as indices gained across the US, Europe and Asia. Fixed income markets also rallied, with two-year and 10-year government bond yields moving a touch lower. The coordinated move across asset classes reflects a partial unwinding of the immediate escalation risk that had been priced in late March and early April.
With the initial market reaction now behind us, attention turns to durability. The de-escalation has been welcomed by investors, but significant hurdles in reaching a peace deal suggest that uncertainty will remain elevated.
While Trump suggested that most of the longstanding points of disagreement have been addressed, Iran’s reported 10-point proposal contains conditions that had previously been unacceptable to the US and its allies, including lifting all sanctions, maintaining Iranian control over the Strait of Hormuz, and imposing no restrictions on the country’s stockpile of enriched uranium. This stands in sharp contrast to the US administration’s 15-point peace framework from March, which called for Iran to cease threats to shipping, surrender enriched uranium, dismantle nuclear facilities, accept limits on its missile programme and end support for regional proxy groups.
Whether these competing positions can be reconciled will be central to determining if the current pause evolves into a more permanent settlement or merely delays further confrontation.
Shipping through the Strait of Hormuz remains a critical test case. Prior to the conflict, close to 100 ships transited the Strait daily without requiring coordination with the Iranian military.2 While traffic is likely to increase from the limited flows seen in recent days, a rapid return to pre-conflict volumes appears unlikely given lingering security concerns, insurance costs and operational uncertainties. This could mean that oil and gas prices remain elevated over the coming months, which will feed through to inflation.
The ceasefire has clearly reduced the immediate tail risk of broader regional conflict, as reflected in the rebound across risk assets and the pullback in oil prices. However, negotiations remain at an early stage and key points of contention persist. As such, while markets have moved on, volatility is likely to remain elevated as investors assess the credibility and durability of the diplomatic process.
For long-term investors, periods of geopolitical stress can feel unsettling, but history suggests that maintaining discipline through episodes of volatility is often rewarded. Sharp market dislocations can create opportunities to add to assets at more attractive valuations.
[1] Bloomberg, Deutsche Bank
[2] Gavekal Research
LGT Wealth Management UK LLP is authorised and regulated by the Financial Conduct Authority Registered in England and Wales: OC329392. Registered office: 14 Cornhill, London, EC3V 3NR. LGT Wealth Management Limited is authorised and regulated by the Financial Conduct Authority. Registered in Scotland number SC317950 at Capital Square, 58 Morrison Street, Edinburgh, EH3 8BP. LGT Wealth Management Jersey Limited is incorporated in Jersey and is regulated by the Jersey Financial Services Commission in the conduct of Investment Business and Funds Service Business: 102243. Registered office: Sir Walter Raleigh House, 48-50 Esplanade, St Helier, Jersey JE2 3QB. LGT Wealth Management (CI) Limited is registered in Jersey and is regulated by the Jersey Financial Services Commission: 5769. Registered Office: at Sir Walter Raleigh House, 48 – 50 Esplanade, St Helier, Jersey JE2 3QB. LGT Wealth Management US Limited is authorised and regulated by the Financial Conduct Authority and is a Registered Investment Adviser with the US Securities & Exchange Commission (“SEC”). Registered in England and Wales: 06455240. Registered Office: 14 Cornhill, London, EC3V 3NR.
This communication is provided for information purposes only. The information presented is not intended and should not be construed as an offer, solicitation, recommendation or advice to buy and/or sell any specific investments or participate in any investment (or other) strategy and should not be construed as such. The views expressed in this publication do not necessarily reflect the views of LGT Wealth Management US Limited as a whole or any part thereof. Although the information is based on data which LGT Wealth Management US Limited considers reliable, no representation or warranty (express or otherwise) is given as to the accuracy or completeness of the information contained in this Publication, and LGT Wealth Management US Limited and its employees accept no liability for the consequences of acting upon the information contained herein. Information about potential tax benefits is based on our understanding of current tax law and practice and may be subject to change. The tax treatment depends on the individual circumstances of each individual and may be subject to change in the future.
All investments involve risk and may lose value. Your capital is always at risk. Any investor should be aware that past performance is not an indication of future performance, and that the value of investments and the income derived from them may fluctuate, and they may not receive back the amount they originally invested.