Last year, I wrote about some of the key trends impacting the luxury goods market. Many luxury goods companies, whose stock market listings we follow, experienced strong sales growth throughout the pandemic as consumers spent large amounts of disposable income on luxury goods – given the associated restrictions on travel, dining and entertainment spending. This surge in demand began to fall away as societies reopened and consumers were able to travel, dine out and socialise again.
In this article, I take a closer look at the increasingly important, other side to luxury – luxury experiences. Now growing at a faster rate than luxury goods, luxury experiences are tapping into the preferences of ultra-high-net-worth (UHNW) individuals seeking unique and curated experiences. Luxury experiences can range from fine dining, wellness-retreats, VIP sporting or cultural events, and high-end travel - including five-star hotels and the chartering of private jets and superyachts. McKinsey estimates that spending on luxury hospitality will exceed $390bn in 2028, which equates to growth of +33% (or +6% per annum) from the $293bn spent in 2023. From Bain’s 2024 luxury report, they estimated that the only luxury segments set to grow were all linked to experiences.
The cornerstones to luxury’s success remains exclusivity, quality and status signalling. Luxury goods have long conveyed status, whether through logos on clothing or leather goods acting as ‘social signals’ for the wearer, or ‘quiet luxury’ brands that prioritise ultra discreet branding (where only the initiated would recognise the brand). The unquantifiable membership to this ‘in the know’ sector of society is increasingly becoming the more powerful signal. Experiences are harder to replicate, more difficult to access and, in many cases, more socially distinctive.
Consumers are now seeking rare, personalised experiences; consider concierge services, ultra-luxury boutique hotels or private members’ clubs that offer privacy and exclusivity. Luxurious members clubs and hotel groups blend heritage grandeur with privacy and exclusivity. Soaring demand from global UHNW members reflects the growing preference for rarefied, sometimes invitation-only environments offering access to high levels of discretion and highly personalised experiences that go far beyond traditional hospitality.
Luxury experiences have always existed, but one of the reasons they are gaining more traction is that they are far more visible than they were 15 years ago. Social media has made it easier to share unique experiences, particularly amongst the younger generations. In this sense, luxury spending is no longer only about ownership but the ability to display access. That is particularly relevant for UHNW individuals, whose social media presence often reinforces the exclusivity of the experiences they can access.
Millennials in particular are prioritising ‘memory making’ over material possessions.
This presents opportunities for those in luxury experience sectors, and challenges for more traditional goods brands. This explains why high-end brands are moving further into luxury hospitality, yachts and beach clubs, with names such as LVMH, Bulgari and Armani seeking to monetise the wider customer experience. In parallel, private members’ clubs and curated, invitation-only spaces are seeing strong demand, reinforcing the importance of scarcity, service and access in luxury spending.
The luxury industry has grown ahead of global GDP over the past decade1 and within this growth, the highest spenders (categorised as spending >€70,000/year) have contributed between 40-50%.2 This trend is set to continue and, as estimated from McKinsey’s report, the >€70,000 cohort will be the major contributors to growth (65-80% to 2027). This is incrementally positive for luxury experiences given the exclusive and scarce nature of this segment within the broader luxury sector.
Another facet to the growth of luxury experiences has been a shift in consumer mindset towards assessing both value and quality – the ‘luxury equation’. After several years of price increases and higher inflation, consumers are more selective about whether a purchase feels justified. If you have had to endure price rises, but there is no tangible or commensurate increase in quality, there is a risk that the purchase and/or ownership of the luxury good could be somewhat anticlimactic.
McKinsey reports that ~80% of HNWIs have said they expect to “shift a greater proportion of their luxury spending to experiences and wellness”. Experiences have the ability to offer a potentially longer lasting emotional value and/or benefit for consumers. For many UHNW and HNW individuals, who might already own many luxury goods, there could be a diminishing marginal return or utility derived from each subsequent luxury purchase. However, as experiences are typically unique, they offer more exclusivity which in turn can add to the utility or value to the consumer. The chart below shows that lifestyle categories, as highlighted in red, typically score well on the acquisition and engagement scale compared to tangible goods.
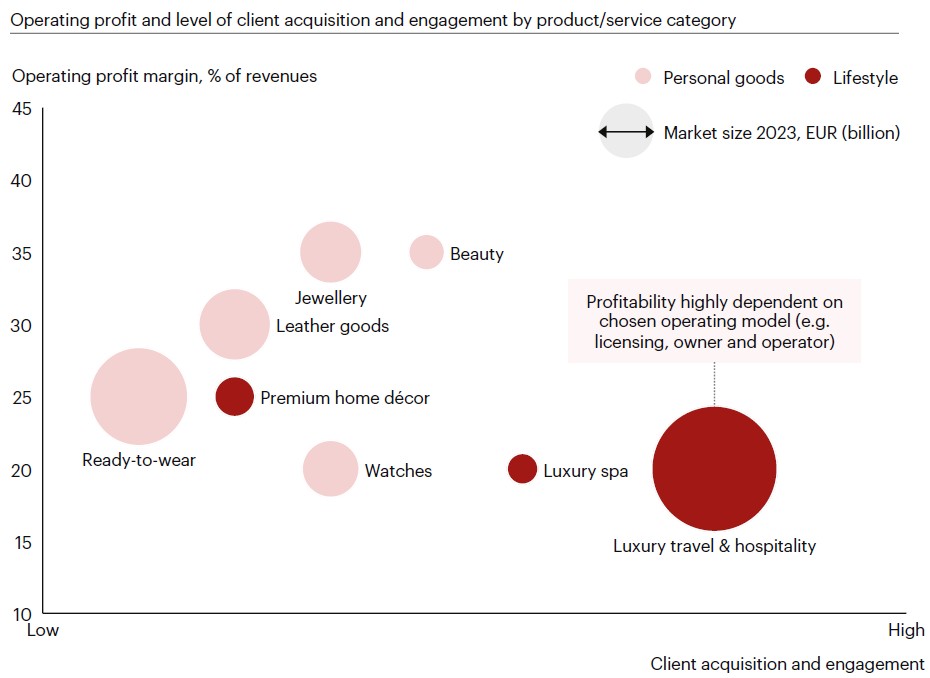
The question which consumers appear to be asking more and more is “will this purchase improve my life?”. Though difficult to quantify, it underscores the growing connection between luxury and wellness. Beyond occasional high‑end travel, consumers are now investing in holistic wellbeing through longevity clinics, retreats and premium beauty treatments. Spending on self‑care not only supports physical and emotional health but also strengthens the sense of justification behind such expenditures.
The evolving drivers of the luxury market are unlikely to fade. Greater visibility, increasingly unique and exclusive experiences, coupled with consumers’ growing focus on health and wellness, should continue to propel experiential spending. This is not to suggest that traditional luxury goods face structural decline – rather, the dynamics of luxury are shifting as the consumer evolves.
[1] Page 11 McKinsey & Company and Business of Fashion, 'State of Fashion Luxury' - 2025
[2] Page 11 McKinsey & Company and Business of Fashion, 'State of Fashion Luxury' - 2025
LGT Wealth Management UK LLP is authorised and regulated by the Financial Conduct Authority Registered in England and Wales: OC329392. Registered office: 14 Cornhill, London, EC3V 3NR. LGT Wealth Management Limited is authorised and regulated by the Financial Conduct Authority. Registered in Scotland number SC317950 at Capital Square, 58 Morrison Street, Edinburgh, EH3 8BP. LGT Wealth Management Jersey Limited is incorporated in Jersey and is regulated by the Jersey Financial Services Commission in the conduct of Investment Business and Funds Service Business: 102243. Registered office: Sir Walter Raleigh House, 48-50 Esplanade, St Helier, Jersey JE2 3QB. LGT Wealth Management (CI) Limited is registered in Jersey and is regulated by the Jersey Financial Services Commission: 5769. Registered Office: at Sir Walter Raleigh House, 48 – 50 Esplanade, St Helier, Jersey JE2 3QB. LGT Wealth Management US Limited is authorised and regulated by the Financial Conduct Authority and is a Registered Investment Adviser with the US Securities & Exchange Commission (“SEC”). Registered in England and Wales: 06455240. Registered Office: 14 Cornhill, London, EC3V 3NR.
This communication is provided for information purposes only. The information presented is not intended and should not be construed as an offer, solicitation, recommendation or advice to buy and/or sell any specific investments or participate in any investment (or other) strategy and should not be construed as such. The views expressed in this publication do not necessarily reflect the views of LGT Wealth Management US Limited as a whole or any part thereof. Although the information is based on data which LGT Wealth Management US Limited considers reliable, no representation or warranty (express or otherwise) is given as to the accuracy or completeness of the information contained in this Publication, and LGT Wealth Management US Limited and its employees accept no liability for the consequences of acting upon the information contained herein. Information about potential tax benefits is based on our understanding of current tax law and practice and may be subject to change. The tax treatment depends on the individual circumstances of each individual and may be subject to change in the future.
All investments involve risk and may lose value. Your capital is always at risk. Any investor should be aware that past performance is not an indication of future performance, and that the value of investments and the income derived from them may fluctuate, and they may not receive back the amount they originally invested.