For most people - even the devotees of the FT - reading about technical analysis can be about as exciting as watching paint dry. However, the sharp market moves following the US midterms have prompted us to tackle the subject anyway. Beneath the headline index returns lies an evolving market structure where we believe that the recent falls may reflect a healthy rotation in market leadership rather than a wider market sell-off or investors shifting to the safety of cash. By rotation, we mean investors shifting their attention from one area of the market to another. Whether it persists or not is another question.
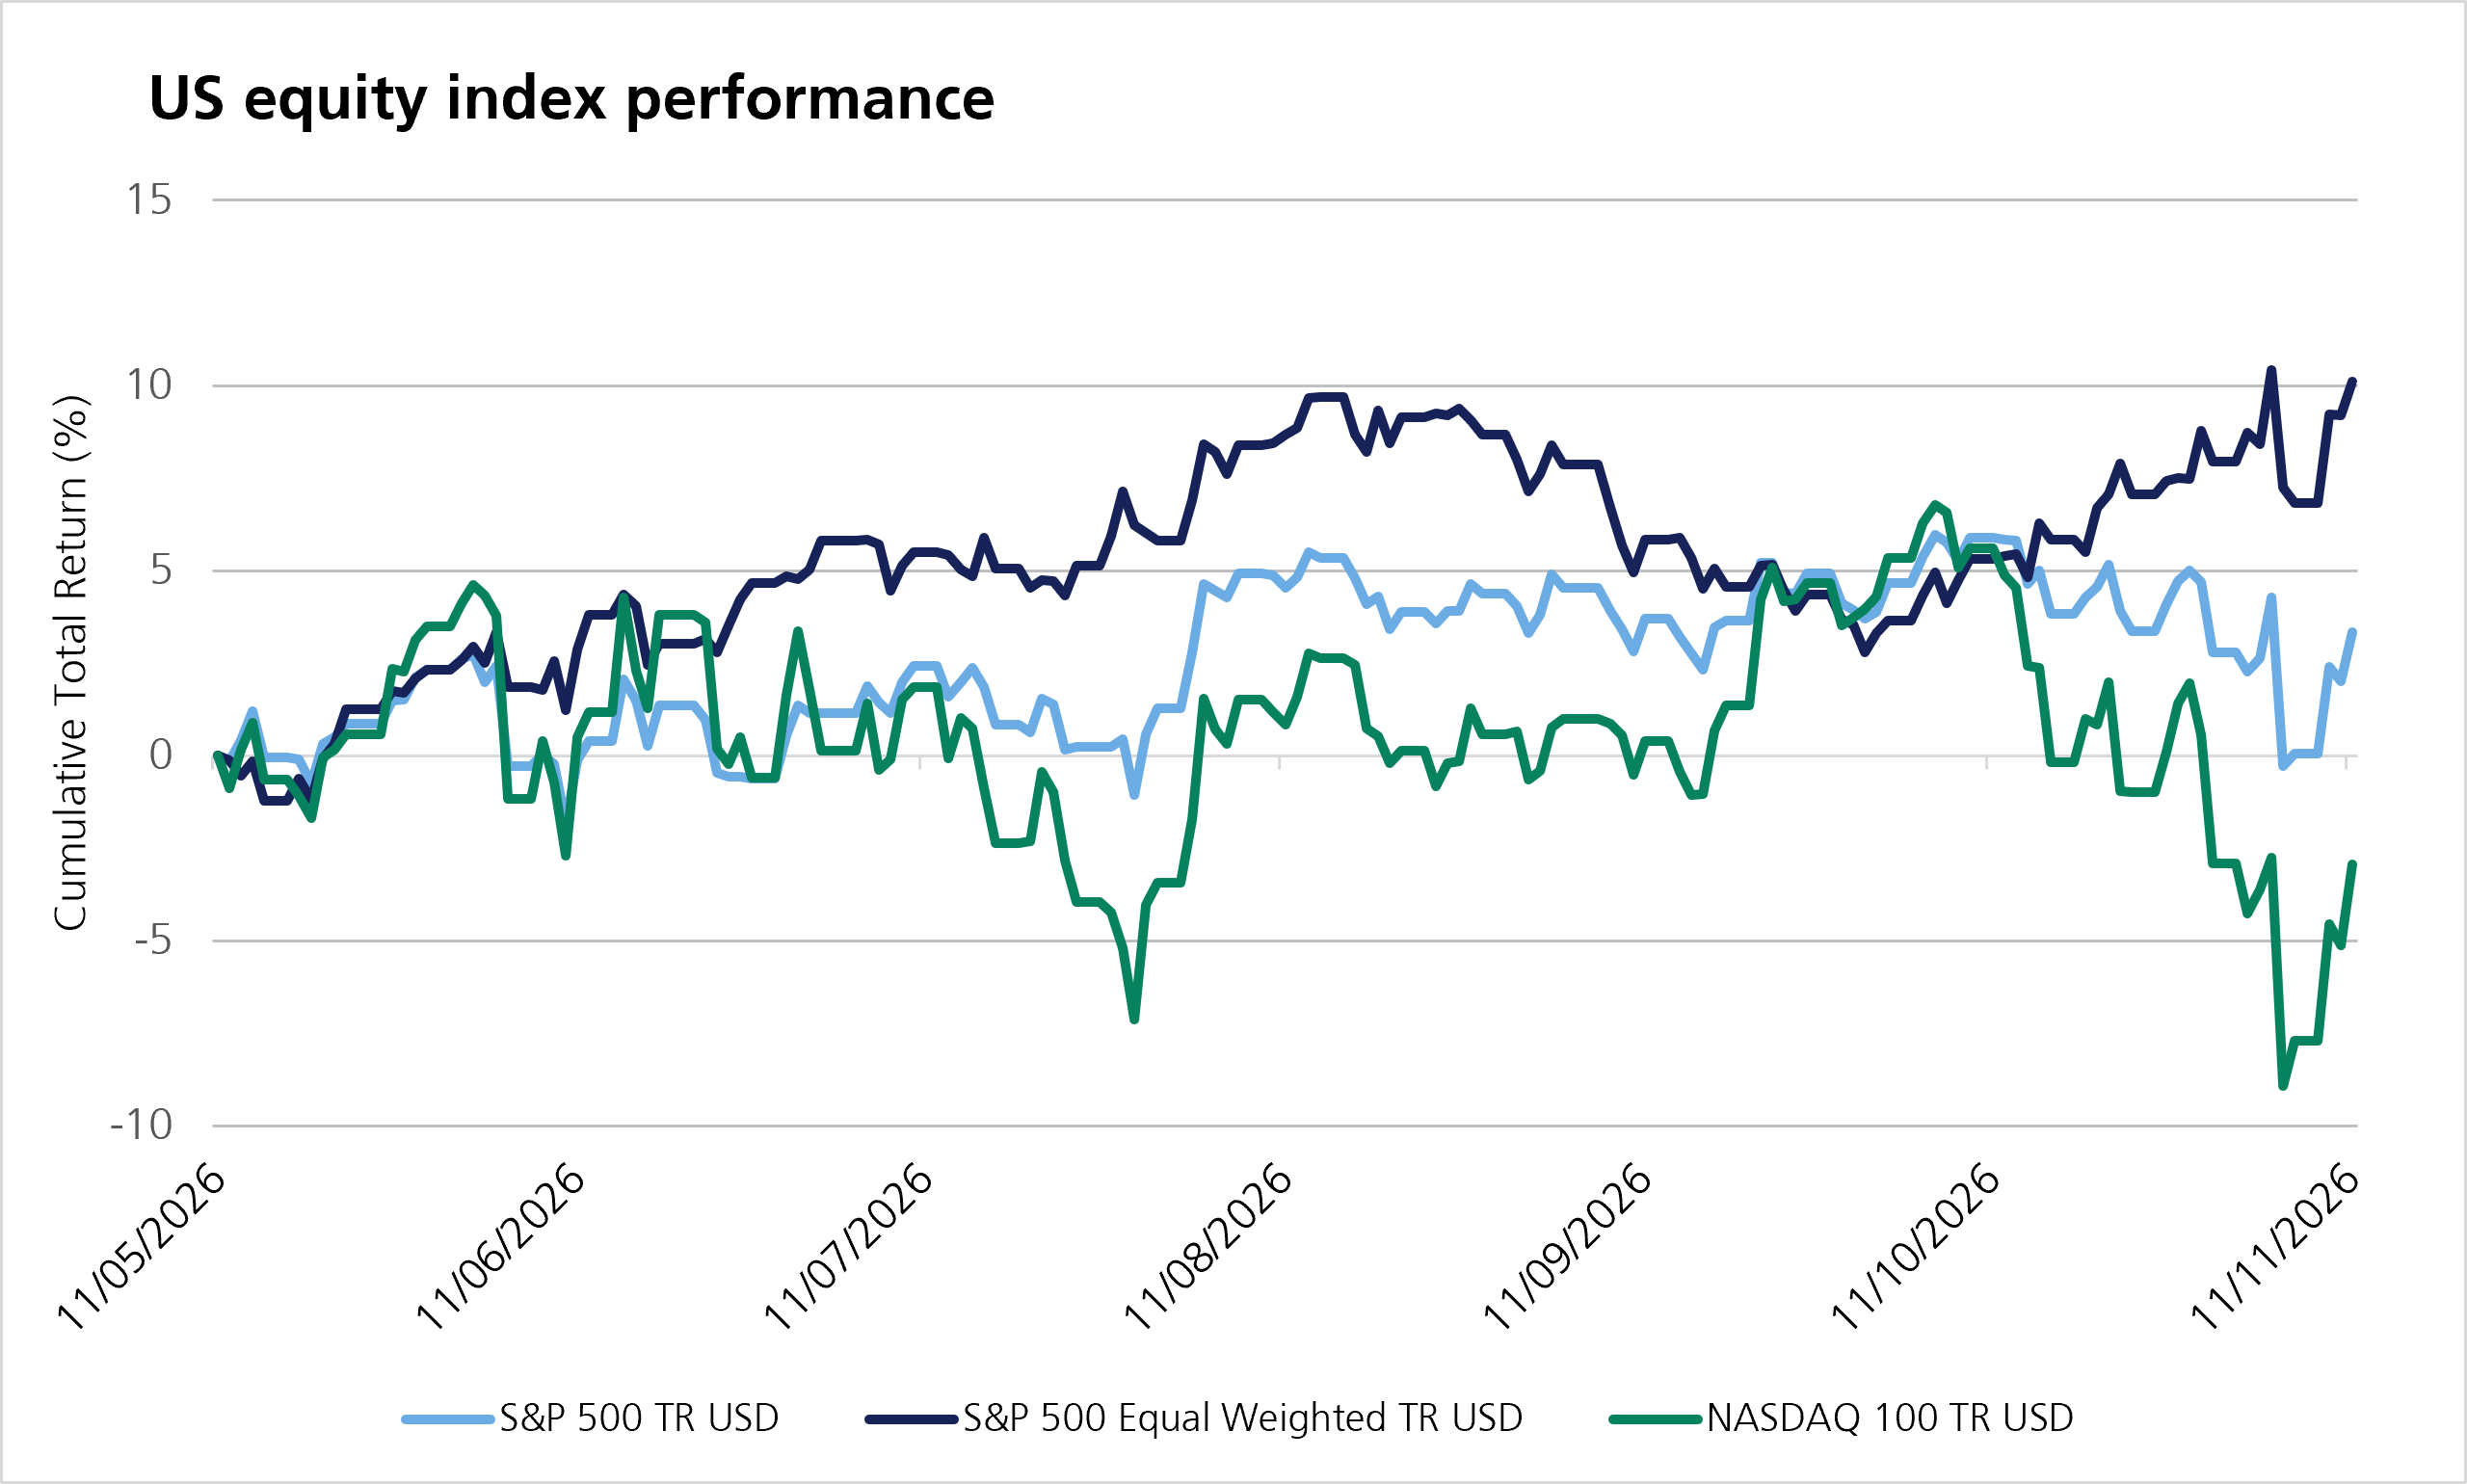
We believe this is one of the most notable rotational markets in recent memory. Rather than shares moving up or down together, leadership has been changing rapidly, with yesterday’s winners falling out of favour, while neglected parts of the market are attracting attention. The last week or so, since the results of the US midterms, has brought this rotation into sharp focus. But the story did not start with the midterms. As the chart below shows, signs of this rotation appeared over the summer, and the shifts accelerated in October. So, what is happening under the bonnet?
The distinction between an index’s returns and the performance of its underlying stocks can be particularly revealing. For example, despite the recent Nasdaq decline, 61.7% of S&P 500 constituents were trading above their own 200-day moving averages at the end of October. In other words, most shares remained above a widely watched measure of their longer-term trend. This reading predates the midterms and suggests that signs of broader participation were already visible before the election. Another recent reading of market breadth showed around half of S&P 500 constituents reaching 20-day highs, even while AI-related shares remained under pressure. These readings could change, but for now the weakness among yesterday’s leaders is coinciding with gains elsewhere.
Because the S&P 500 weights companies by market value, falls in a few heavyweight stocks can disproportionately affect both the headline index and the headlines it generates - even when many other constituents are advancing. The S&P 500 Equal Weight Index, which gives each company approximately the same weight, offers a useful comparison: it remains close to its all-time high despite the recent decline in its market-cap-weighted counterpart. This divergence is consistent with rotation between sectors rather than indiscriminate weakness across equities. We would view this broadening of market leadership as a positive development.
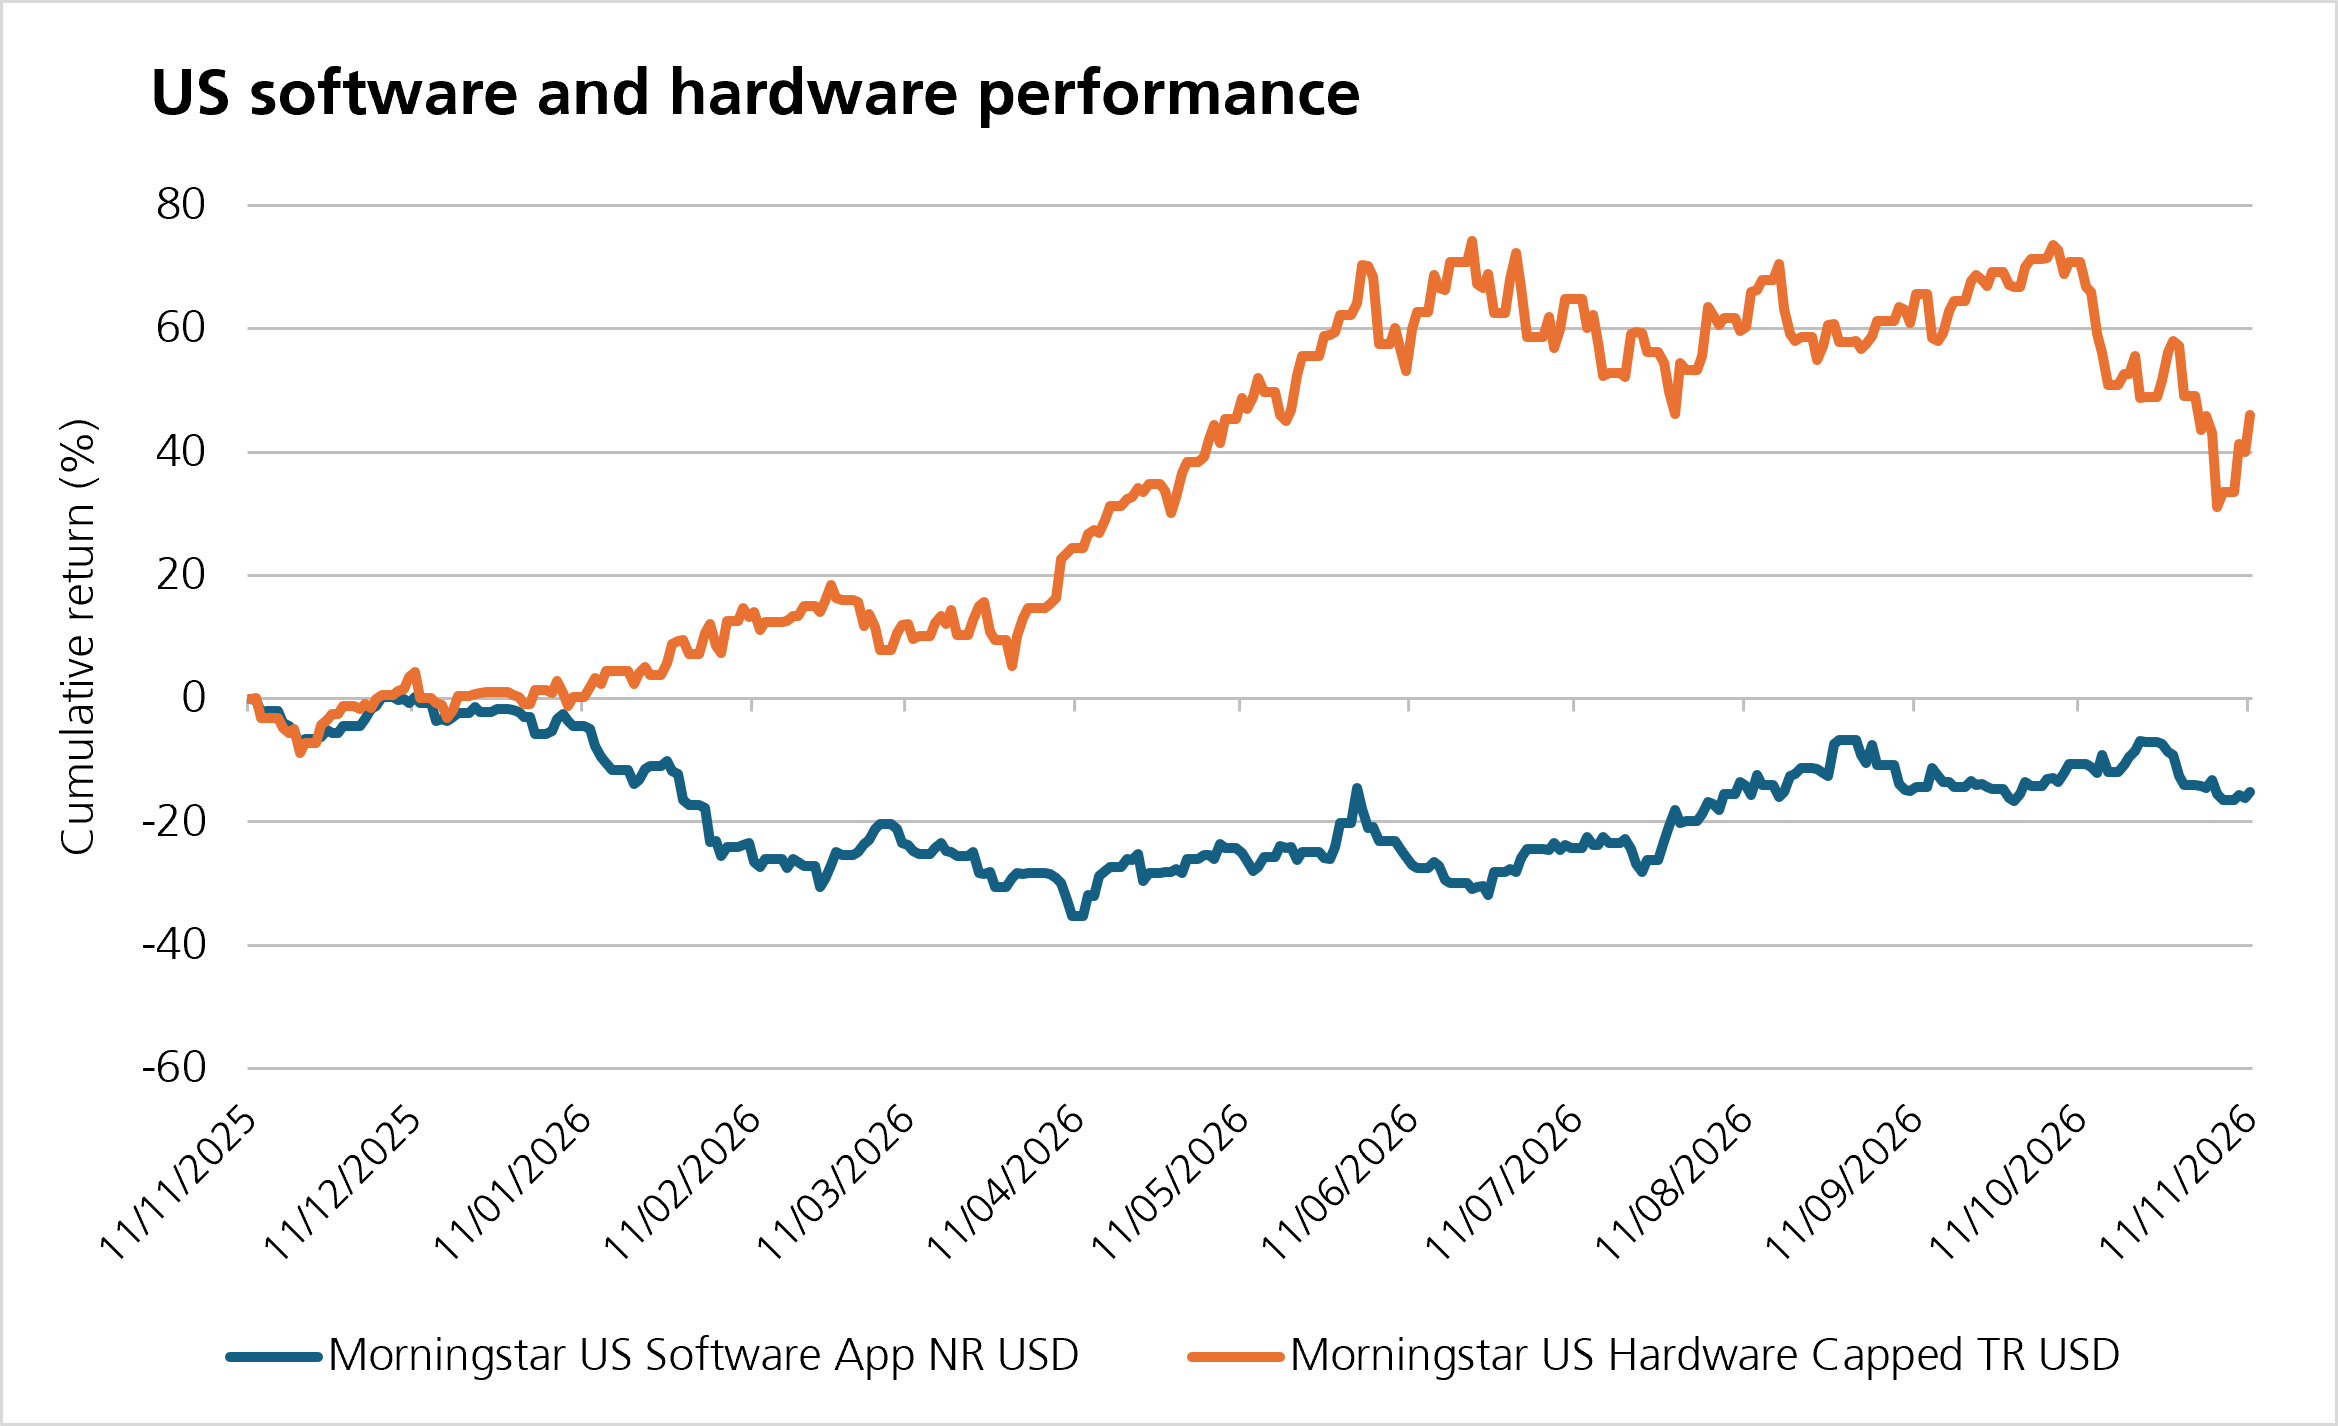
Technology is often discussed as though it were a single investment theme. This year has shown otherwise, with clear winners and losers emerging across its subsectors. Software companies, semiconductor manufacturers, data-centre operators, and large platforms have different business models, valuations and vulnerabilities. For much of the recent AI boom, investors rewarded companies expected to benefit from building the infrastructure: chips, computing power and data centres. These hardware and infrastructure businesses led through the first half of the year, while software came under pressure.
More recently, however, that leadership has begun to reverse. As the chart below shows, some hardware and infrastructure names have come under pressure, while parts of software and the large platforms have attracted renewed interest. One possible explanation is that investors are reassessing the balance between the substantial spending required to build AI infrastructure and the returns that spending will ultimately generate. The midterms have also raised questions about future data-centre regulation. How this trend plays out could have a big impact on how markets move on from here.
The rotation extends beyond technology. Global consumer staples rose 10.6% in October, while healthcare gained 9.8%. Alongside insurance, these sectors have attracted renewed attention after spending years in the shadow of the market’s growth darlings. Consumer staples represented approximately 14% of the S&P 500 in 2009; by January 2026, their weight had fallen to 4.6%. By September, staples and consumer discretionary together accounted for just 13% - a 36-year low. This illustrates how much their representation in the index has diminished.
Investors may therefore hold hundreds of companies through an index fund, yet have relatively little exposure to everyday consumer businesses compared with previous decades. Meanwhile, portfolios that track indices weighted by company size have inherited the growing concentration in technology and AI-related stocks. That is a substantial change in what owning “the market” means.
So why are these more defensive sectors attracting attention now? Defensive sectors are often seen as relatively resilient during periods of economic uncertainty, although their shares can still fall in value. Investors may be rebalancing towards neglected areas while reassessing the spending commitments, valuations and potential disruption associated with AI. Businesses whose earnings depend less directly on the AI investment cycle offer a different set of exposures. There may also be a more conventional explanation: in an uncertain environment, investors place greater value on dependable demand and relatively predictable earnings. Staples, healthcare and parts of insurance can often offer those characteristics. The rotation may therefore reflect both a reassessment of technology and a rediscovery of what the rest of the market has to offer.
The returns achieved by headline indices like the S&P 500 so far this year belie the significant scale of the moves beneath the surface. Even when a small number of large companies come under pressure, other areas of the market can perform differently. Following the midterms, we believe it is too early to make a wholesale pivot in portfolio strategy, particularly while markets remain volatile. Our view has been to have meaningful exposure to bonds and equities outside the US which are both potential diversifiers if leadership broadens beyond US technology.
The midterms may nevertheless mark the continuation of a more durable shift in leadership. We remain alert to that possibility and can adjust portfolios if the evidence warrants a change of course. For now, the evidence points to a highly rotational market but it is uncertain whether it will persist. If a broader range of companies, including previously overlooked businesses with attractive valuations, were to lead market gains, we would view that as healthy. It could also mark the start of an environment where active management starts to outperform passive indices again. The challenge is distinguishing a lasting change from a noisy change in sentiment.
LGT Wealth Management UK LLP is authorised and regulated by the Financial Conduct Authority Registered in England and Wales: OC329392. Registered office: 14 Cornhill, London, EC3V 3NR. LGT Wealth Management Limited is authorised and regulated by the Financial Conduct Authority. Registered in Scotland number SC317950 at Capital Square, 58 Morrison Street, Edinburgh, EH3 8BP. LGT Wealth Management Jersey Limited is incorporated in Jersey and is regulated by the Jersey Financial Services Commission in the conduct of Investment Business and Funds Service Business: 102243. Registered office: Sir Walter Raleigh House, 48-50 Esplanade, St Helier, Jersey JE2 3QB. LGT Wealth Management (CI) Limited is registered in Jersey and is regulated by the Jersey Financial Services Commission: 5769. Registered Office: at Sir Walter Raleigh House, 48 – 50 Esplanade, St Helier, Jersey JE2 3QB. LGT Wealth Management US Limited is authorised and regulated by the Financial Conduct Authority and is a Registered Investment Adviser with the US Securities & Exchange Commission (“SEC”). Registered in England and Wales: 06455240. Registered Office: 14 Cornhill, London, EC3V 3NR.
This communication is provided for information purposes only. The information presented is not intended and should not be construed as an offer, solicitation, recommendation or advice to buy and/or sell any specific investments or participate in any investment (or other) strategy and should not be construed as such. The views expressed in this publication do not necessarily reflect the views of LGT Wealth Management US Limited as a whole or any part thereof. Although the information is based on data which LGT Wealth Management US Limited considers reliable, no representation or warranty (express or otherwise) is given as to the accuracy or completeness of the information contained in this Publication, and LGT Wealth Management US Limited and its employees accept no liability for the consequences of acting upon the information contained herein. Information about potential tax benefits is based on our understanding of current tax law and practice and may be subject to change. The tax treatment depends on the individual circumstances of each individual and may be subject to change in the future.
All investments involve risk and may lose value. Your capital is always at risk. Any investor should be aware that past performance is not an indication of future performance, and that the value of investments and the income derived from them may fluctuate, and they may not receive back the amount they originally invested.