The global space economy is entering a new phase, fuelled by technological innovation and growing private-sector investment. The race for space is no longer simply between the world’s superpowers: new commercial rivalries are emerging as private companies compete to access opportunities in orbit.
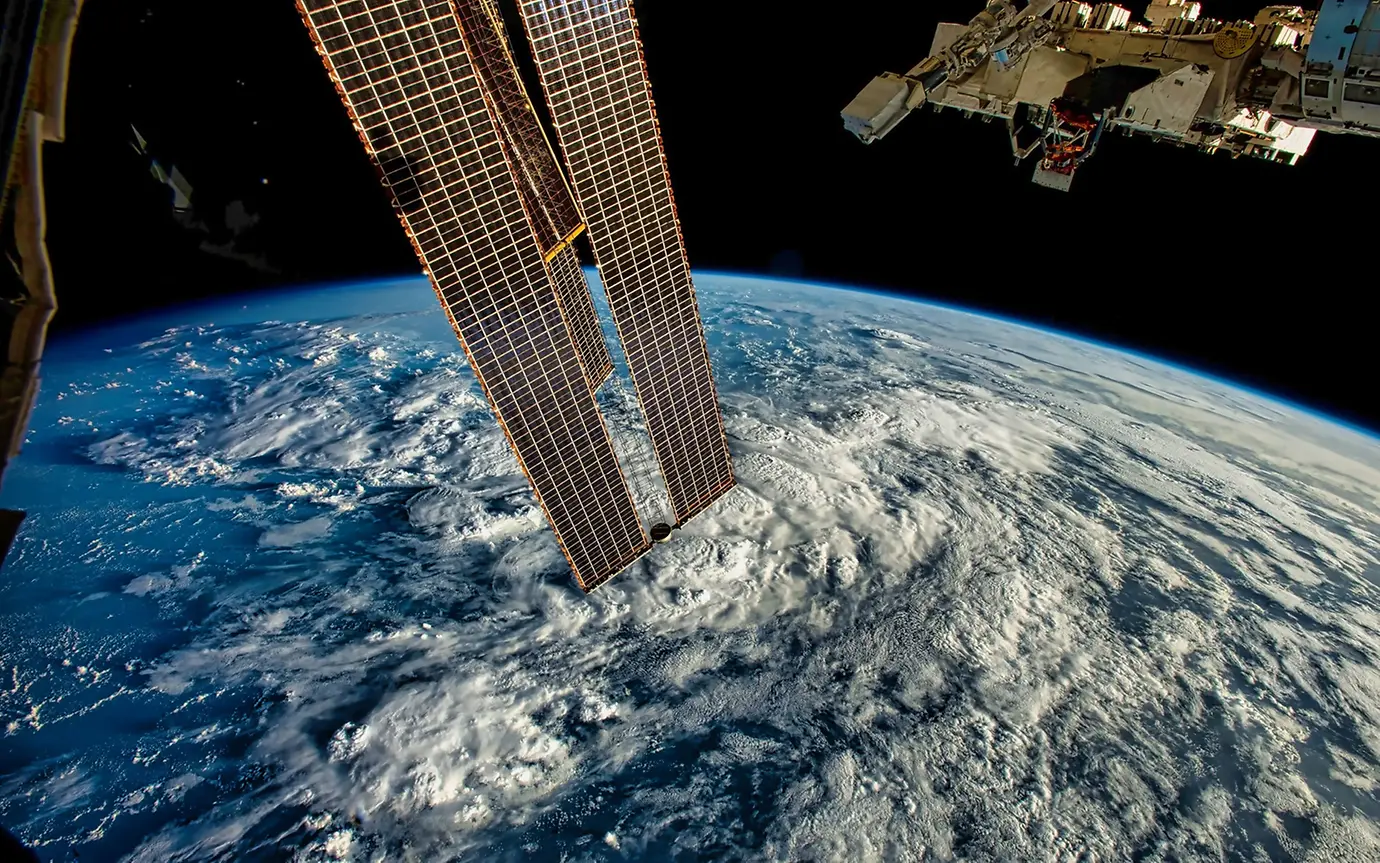
More than 50 years after the last human set foot on the Moon, the space race is entering a new era. Unlike the previous contest between the United States and the Soviet Union, the objective has evolved beyond leaving footprints and flags. The goals today are to use the Moon as a staging post for deeper space exploration and as a laboratory for commercial experimentation.
The recent Artemis II mission saw NASA successfully launch the first crewed mission to travel beyond low Earth orbit (LEO) since 1972. This was the critical first step towards establishing a permanent base near the lunar south pole, where water ice deposits can provide drinking water and rocket propellant.
China also has its sights set on the Moon, with a commitment to becoming the world’s leading space power by 2045.
It is tempting to draw parallels with the Cold War space race, with China taking the place of the Soviet Union, however the comparison only goes so far. Space race 2.0 is built on technological advances made by the private sector, which is itself eager to exploit commercial opportunities in space.
While companies have long been involved in space programmes, building engines and supplying components, the nature of that involvement has fundamentally changed. A new generation of businesses now designs, owns and operates its own rockets and spacecraft.
In the USA, this shift was driven by budget pressures, safety concerns and strategic necessity. After the retirement of the Space Shuttle, NASA chose to buy services from private providers. Although this meant that companies assumed more technical and financial risk, it also allowed them to market their capabilities to other customers and pursue commercial opportunities.
These programmes signalled a structural shift in the space industry. Governments remain anchor customers and regulators, but increasingly act as buyers in a commercial market. This change in procurement has been a major catalyst for the space economy.
Fixed price contracts and the prospect of serving multiple customers have created strong incentives for companies to reduce costs and increase launch frequency. Reusable rockets, the standardisation of components and more efficient manufacturing have further reduced costs. Together, these advances have significantly lowered the cost of reaching orbit.
Depending on the data and baseline used, the cost per kilogram of reaching LEO with modern reusable launchers is up to 90% lower than 20 years ago. Cheaper access to space not only accelerates exploration but also opens up a broad range of commercial opportunities for private companies.
To better understand the continuing evolution of the space economy, we can split the market into three segments:
• Enabling technologies and infrastructure that form the backbone of the space economy
• Commercial applications built on space infrastructure across a wide range of industries on Earth
• Frontier technologies aimed at long-term opportunities that could redefine the space economy’s boundaries
For most of spaceflight history, rockets were built by large defence contractors under cost-plus government contracts, where, for example, one company served as the prime contractor for the core stage, with other firms supplying other parts or subsystems. This model still exists, but the commercial era has given rise to more vertically integrated operators that design, manufacture, launch and operate payloads. These players have been able to increase launch frequency while controlling costs.
Higher launch frequency creates opportunities for the broader supply chain. For example, propulsion and fuel suppliers are critical enablers of every launch, while companies delivering specialty materials and alloys provide high-performance composites and thermal protection systems that can withstand the extreme heat, as well as the stress of launch and atmospheric re-entry.
Satellites were initially launched and operated by governments and state telecom providers using geostationary orbit (GEO) satellites at 35,786 km above the equator. However, states no longer have a monopoly on space. New commercial challengers are not only reshaping the launch model, but also the satellite industry, as they race to deploy satellite constellations in LEO at altitudes of 160 to 2000 km.
Lower launch costs and high-volume manufacturing of smaller, software-defined satellites make it possible to deploy large constellations in LEO. Thousands of interconnected satellites orbiting closer to Earth enable applications such as satellite broadband, providing global internet coverage with performance similar to that of terrestrial networks.
Still, competition to build constellations of LEO satellites is intensifying among commercial and state actors alike. Control of LEO is both commercially attractive as well as strategically important for national security.
Falling launch costs for small satellites, new satellite-based datasets and advances in artificial intelligence (AI) are creating favourable conditions for the EO market to grow. EO satellites capture data about physical conditions and changes on Earth using different onboard sensors, while global navigation satellite systems (GNSS) provide precise location and timing information.
The surge in data collected through these satellites exceeds human analytical capabilities, making AI essential to unlock value. This is why commercial applications are increasingly combining EO data, GNSS and AI-driven analytics to turn raw observations into actionable insights in areas as diverse as agriculture (e.g. detecting crop stress requiring irrigation); insurance (e.g. for remote damage inspection); environmental monitoring (e.g. detecting methane leaks from oil infrastructure) and defence (e.g. for military surveillance).
Falling launch costs are also encouraging companies and governments to explore the use of future technologies in space. The properties of space could make it an attractive location for infrastructure and services, while offering ways to address resource scarcity.
These ideas remain highly speculative and face significant technical, regulatory and commercial hurdles. Nevertheless, they illustrate how cheaper and more frequent access to space could broaden the boundaries of the space economy.
Ideas include:
• Space-based solar power: generating electricity in orbit and beaming it to Earth via microwaves or lasers. In theory, this would deliver clean power; in practice, it comes with major challenges, including large-scale in-orbit assembly and transmission inefficiencies.
• Orbital data centres: moving energy-intensive infrastructure into space to address growing constraints around energy, cooling, land and grid connections. Issues include the need for electronics that can withstand radiation, heat rejection in vacuum and the complexity of servicing, upgrading and replacing hardware in space.
• In-space manufacturing: placing production processes in space to benefit from the microgravity, vacuum and extreme thermal conditions that are difficult to replicate on Earth. Viability will depend on whether the benefits outweigh the costs.
• Asteroid and lunar mining: using off-world resource extraction to support both terrestrial supply chains and future space infrastructure. Its potential will depend on overcoming significant technological demands, navigating evolving legal frameworks and establishing a viable commercial case.
• Space tourism and logistics: continuing the expansion of human spaceflight beyond government missions into commercial activity, including suborbital tourism, although orbital missions remain highly complex and expensive. Demand, safety, insurance costs and regulation pose key challenges.
While these visionary ideas are promising, they all face technical, regulatory and commercial hurdles, and rely on further reductions in the cost of putting heavy infrastructure into orbit. Clearly, fully reusable launch systems with larger payload capacity will be crucial.
The space economy is developing rapidly, but the longer-term trajectory of frontier technologies remains uncertain. What is clear is that more frequent, lower-cost access to space is expanding the range of possible applications and reshaping how companies and governments approach infrastructure, data and innovation, both in space and on Earth.
LGT Wealth Management UK LLP is authorised and regulated by the Financial Conduct Authority Registered in England and Wales: OC329392. Registered office: 14 Cornhill, London, EC3V 3NR. LGT Wealth Management Limited is authorised and regulated by the Financial Conduct Authority. Registered in Scotland number SC317950 at Capital Square, 58 Morrison Street, Edinburgh, EH3 8BP. LGT Wealth Management Jersey Limited is incorporated in Jersey and is regulated by the Jersey Financial Services Commission in the conduct of Investment Business and Funds Service Business: 102243. Registered office: Sir Walter Raleigh House, 48-50 Esplanade, St Helier, Jersey JE2 3QB. LGT Wealth Management (CI) Limited is registered in Jersey and is regulated by the Jersey Financial Services Commission: 5769. Registered Office: at Sir Walter Raleigh House, 48 – 50 Esplanade, St Helier, Jersey JE2 3QB. LGT Wealth Management US Limited is authorised and regulated by the Financial Conduct Authority and is a Registered Investment Adviser with the US Securities & Exchange Commission (“SEC”). Registered in England and Wales: 06455240. Registered Office: 14 Cornhill, London, EC3V 3NR.
This communication is provided for information purposes only. The information presented is not intended and should not be construed as an offer, solicitation, recommendation or advice to buy and/or sell any specific investments or participate in any investment (or other) strategy and should not be construed as such. The views expressed in this publication do not necessarily reflect the views of LGT Wealth Management US Limited as a whole or any part thereof. Although the information is based on data which LGT Wealth Management US Limited considers reliable, no representation or warranty (express or otherwise) is given as to the accuracy or completeness of the information contained in this Publication, and LGT Wealth Management US Limited and its employees accept no liability for the consequences of acting upon the information contained herein. Information about potential tax benefits is based on our understanding of current tax law and practice and may be subject to change. The tax treatment depends on the individual circumstances of each individual and may be subject to change in the future.
All investments involve risk and may lose value. Your capital is always at risk. Any investor should be aware that past performance is not an indication of future performance, and that the value of investments and the income derived from them may fluctuate, and they may not receive back the amount they originally invested.