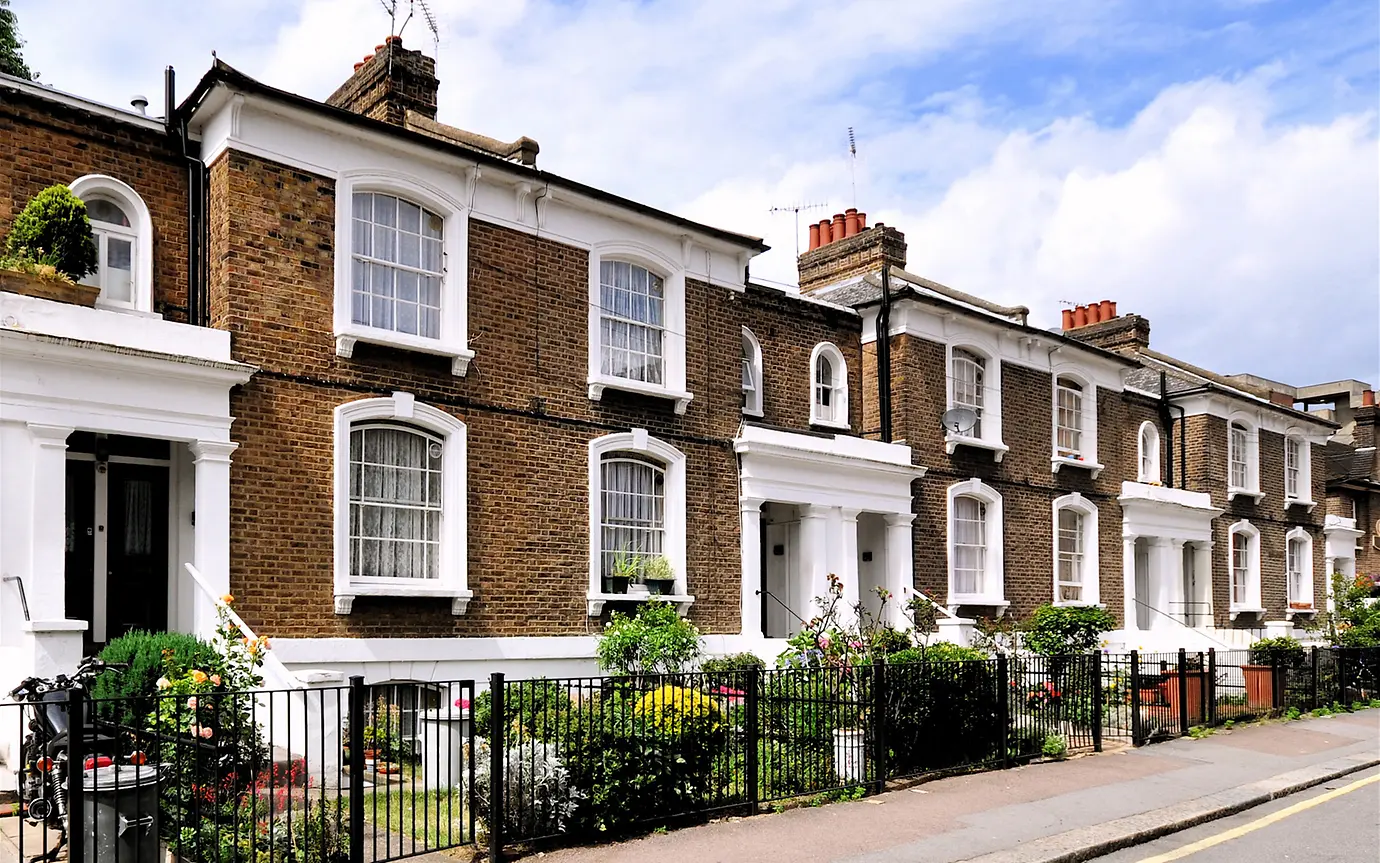
For many US nationals relocating to the UK, the decision about whether to buy a property is often an early and significant milestone. While the UK housing market is accessible to international buyers, the legal process and tax implications differ meaningfully from the US system. For Americans, the added layer of US tax reporting and foreign currency exposure makes advance planning especially important. Below, I set out a high-level overview of the key points to consider.
The structure of the UK property market is not always intuitive for US buyers. Some of the key differences are that real estate agents typically act on behalf of the seller, offers are not legally binding until contracts are exchanged, and there is no escrow system. Instead, solicitors manage the legal due diligence, the exchange of contracts and the transfer of funds.
Most transactions will normally complete within 4-5 months, although additional identity and anti-money laundering checks can extend the timeline for recently arrived or non-resident buyers. Buyers should also be aware of the distinction between freehold and leasehold property, particularly as leasehold ownership may involve ongoing service charges and ground rent.
One of the biggest considerations to bear in mind is that as UK property is purchased in sterling, Americans funding a purchase from US dollars should consider their currency strategy carefully. Working with a specialist foreign exchange provider can help secure more favourable rates and may provide access to forward contracts to manage timing and volatility.
In addition to the purchase price, buyers may face several other additional costs which must be accounted for:
Once you have settled into your new UK property, you’ll find that the differences to US housing extend beyond just the size and age of the buildings. The rules governing property ownership and capital gains also differ from those in the US, including:
Council tax - the UK operates a local property tax called council tax, which is charged by the local authority. In England, the amount you pay is based on the property’s assessed market value as at April 1991, when the regime was first introduced, and the exact rate varies depending on the local area.
Capital gains – the sale of your main home is generally not liable to any capital gains tax under Private Residence Relief. However, the disposal of any additional property is normally chargeable at standard capital gains tax rates.
Inheritance (estate) tax – UK real estate falls within the scope of UK inheritance tax regardless of an individual’s domicile or long-term residency status. The available allowances are significantly lower than those in the US; in broad terms, a deceased individual’s estate may currently benefit from £325,000 of relief, with amounts above this taxed at 40%, subject to a number of conditions and exceptions (such a spousal relief and reliefs on primary residences).3
Expats are subject to worldwide taxation on income and gains, as well as reporting requirements. This complicates the process of buying a house for Americans in the UK. As it stands, the US provides an exemption on the gain of their main residence to $250,000 or $500,000 for a married couple filing jointly. Importantly, this gain is in dollar terms, which leaves people susceptible to currency fluctuations and can potentially create ‘phantom gains’.
Consider a couple who purchased a £3 million property in October 2022 when the exchange rate was 1.12 and later sold it for the same sterling price in October 2025 with the rate at 1.34. For US tax purposes, the IRS would treat the cost basis as $3,360,000 (£3m × 1.12) and the sale proceeds as $4,020,000 (£3m × 1.34), creating a taxable gain of $660,000 - despite there being no gain at all in sterling terms.
Furthermore, paying down or refinancing a foreign-currency mortgage can trigger additional US tax because the IRS treats currency movement on foreign debt as taxable ordinary income. If your GBP mortgage becomes ‘cheaper’ in dollar terms due to exchange rate changes, part of the reduction may be treated as income when the loan is repaid or refinanced - catching many expats off guard. 4
Buying a property in the UK is entirely achievable for Americans looking to make the move, but the interaction between the two tax systems and the influence of currency movements mean that planning is important. In many cases, working with a coordinated team of experts can help ensure the process is managed smoothly. LGT Wealth Management US works closely with a network of with cross-border mortgage brokers, US/UK tax advisers, buying agents and FX specialists to support clients at every stage. Please contact the team here for more information and support with buying a property in the UK.
For broader information on relocating to the UK, please refer to our ‘Moving to the UK: a guide for US expats,’ available for download here.
[1] - Stamp Duty Land Tax: Residential property rates - GOV.UK
[2] - RICS Home Surveys
[3] - How Inheritance Tax works: thresholds, rules and allowances: Overview - GOV.UK
[4] - Why UK mortgages can lead to tax liabilities for US citizens | EY - UK
Please note that the examples given above are based on the laws and system in England; Scotland and Northern Ireland operate under different property purchase regimes, with their own legal processes and requirements.
The information provided above is accurate as of November 2025 but may change as tax and property laws in the UK and US evolve. Please note that this article does not constitute financial or tax advice.
LGT Wealth Management UK LLP is authorised and regulated by the Financial Conduct Authority Registered in England and Wales: OC329392. Registered office: 14 Cornhill, London, EC3V 3NR. LGT Wealth Management Limited is authorised and regulated by the Financial Conduct Authority. Registered in Scotland number SC317950 at Capital Square, 58 Morrison Street, Edinburgh, EH3 8BP. LGT Wealth Management Jersey Limited is incorporated in Jersey and is regulated by the Jersey Financial Services Commission in the conduct of Investment Business and Funds Service Business: 102243. Registered office: Sir Walter Raleigh House, 48-50 Esplanade, St Helier, Jersey JE2 3QB. LGT Wealth Management (CI) Limited is registered in Jersey and is regulated by the Jersey Financial Services Commission: 5769. Registered Office: at Sir Walter Raleigh House, 48 – 50 Esplanade, St Helier, Jersey JE2 3QB. LGT Wealth Management US Limited is authorised and regulated by the Financial Conduct Authority and is a Registered Investment Adviser with the US Securities & Exchange Commission (“SEC”). Registered in England and Wales: 06455240. Registered Office: 14 Cornhill, London, EC3V 3NR.
This communication is provided for information purposes only. The information presented is not intended and should not be construed as an offer, solicitation, recommendation or advice to buy and/or sell any specific investments or participate in any investment (or other) strategy and should not be construed as such. The views expressed in this publication do not necessarily reflect the views of LGT Wealth Management US Limited as a whole or any part thereof. Although the information is based on data which LGT Wealth Management US Limited considers reliable, no representation or warranty (express or otherwise) is given as to the accuracy or completeness of the information contained in this Publication, and LGT Wealth Management US Limited and its employees accept no liability for the consequences of acting upon the information contained herein. Information about potential tax benefits is based on our understanding of current tax law and practice and may be subject to change. The tax treatment depends on the individual circumstances of each individual and may be subject to change in the future.
All investments involve risk and may lose value. Your capital is always at risk. Any investor should be aware that past performance is not an indication of future performance, and that the value of investments and the income derived from them may fluctuate, and they may not receive back the amount they originally invested.