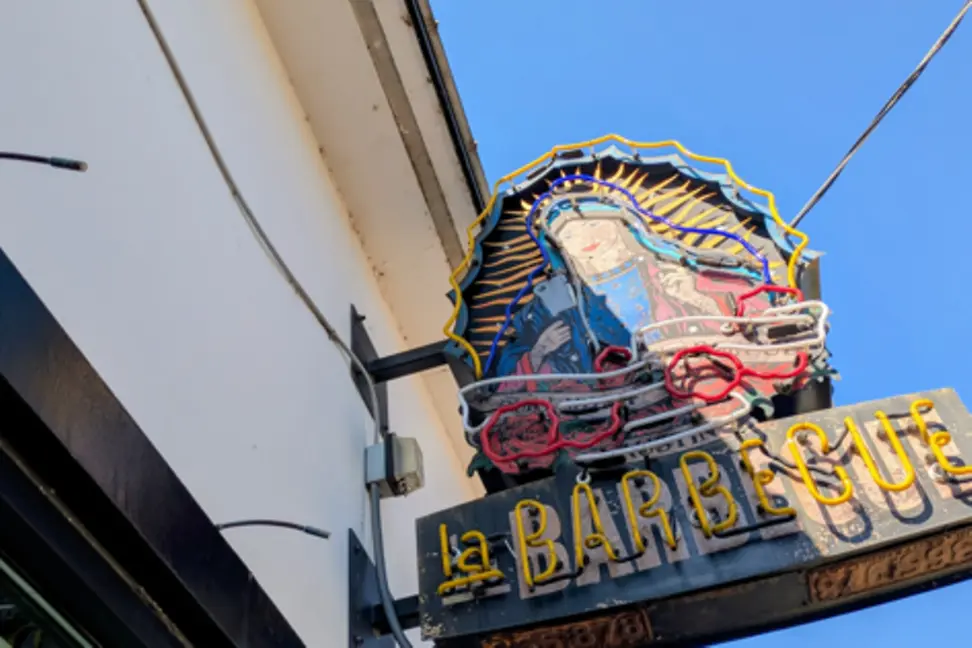
Earlier this year, I travelled across Texas on a long-planned US road-trip. One stop that stayed with me was a visit to La Barbecue in Austin – a BBQ spot that has recently been recognised by the Michelin Guide. At La Barbecue, a pound of brisket cost $36 – a price that reflects not only the craft and expertise of the pitmaster but also the broader pressures affecting beef costs across the US. This mirrors widespread, national headlines about inflation, and local food prices are a reminder that macroeconomic trends have real-world effects.
This trip prompted me to reflect on my exposure to currency fluctuations. While a weaker dollar gave me a boost to my holiday spending money, US tourists visiting London in recent months have found themselves on the less favourable side of this exchange. The same principle applies to UK-based investors holding US dollar–denominated assets. It’s not enough for US equities or bonds to perform well - their value must also be considered in sterling terms too.
The roots of US food inflation in 2025 are a combination of supply constraints (from drought to herd reductions) and persistent demand. The cattle inventory in the United States has dropped to its lowest point in almost 75 years, and the country has seen a decline of over 150,000 cattle ranches since 2017. Government data confirms the trend: US consumer food prices rose 3.1% in the year to September 2025, with beef and steak prices jumping by over 12% and 16% respectively. 1 These increases highlight ongoing supply challenges in the beef industry and a wider pattern of US cost-of-living pressures.
While general US inflation has moderated from its post-pandemic peaks, underlying pressures remain. This has real world consequences: high food price inflation influences consumer sentiment, political debates and, crucially, central bank policy.
Despite the sometimes-conflicting signals from market data, the Federal Reserve (Fed) has continued to ease policy in the second half of 2025, pivoting away from the aggressive tightening seen in prior years. At its latest December meeting, the Federal Open Market Committee (FOMC) delivered a third consecutive 25bp cut, although the decision was not unanimous - with some policymakers arguing for a larger move and others for no change.
This evolving economic landscape has contributed to a softening US dollar. In 2025 we have seen the dollar fall materially against sterling. The US dollar has been weighed down by signs of slowing US growth, political uncertainty and fiscal concerns.
| Date | GBP/USD | % Change (YTD) |
|---|---|---|
| 1 Jan 2025 | 1.25 | — |
| 11 Dec 2025 | 1.34 | +6.9% |
While a weaker US dollar has diminished certain investment returns for UK investors with overseas US holdings, we should remember that for many years prior, a strong dollar has meant a positive tailwind for many UK investors with global portfolios. Of course, for travellers, the currency impact can partly offset the jump in US food prices and get you more brisket per pound, at least for now.
It’s also a reminder that the forces shaping prices on a Texas restaurant’s menu can be the same ones driving global markets.
This year’s brisket bill in Austin reflected more than just a good meal; it was a snapshot of inflation, politics and economic policy at work. For UK investors, the weaker dollar and expectations of lower US interest rates are important reminders to look beyond the headlines, considering both local and global dynamics can give us great insights into the wider investment landscape.
[1] US beef prices are soaring. Will Trump's plans lower them? - BBC News
[2] FactSet
LGT Wealth Management UK LLP is authorised and regulated by the Financial Conduct Authority Registered in England and Wales: OC329392. Registered office: 14 Cornhill, London, EC3V 3NR. LGT Wealth Management Limited is authorised and regulated by the Financial Conduct Authority. Registered in Scotland number SC317950 at Capital Square, 58 Morrison Street, Edinburgh, EH3 8BP. LGT Wealth Management Jersey Limited is incorporated in Jersey and is regulated by the Jersey Financial Services Commission in the conduct of Investment Business and Funds Service Business: 102243. Registered office: Sir Walter Raleigh House, 48-50 Esplanade, St Helier, Jersey JE2 3QB. LGT Wealth Management (CI) Limited is registered in Jersey and is regulated by the Jersey Financial Services Commission: 5769. Registered Office: at Sir Walter Raleigh House, 48 – 50 Esplanade, St Helier, Jersey JE2 3QB. LGT Wealth Management US Limited is authorised and regulated by the Financial Conduct Authority and is a Registered Investment Adviser with the US Securities & Exchange Commission (“SEC”). Registered in England and Wales: 06455240. Registered Office: 14 Cornhill, London, EC3V 3NR.
This communication is provided for information purposes only. The information presented is not intended and should not be construed as an offer, solicitation, recommendation or advice to buy and/or sell any specific investments or participate in any investment (or other) strategy and should not be construed as such. The views expressed in this publication do not necessarily reflect the views of LGT Wealth Management US Limited as a whole or any part thereof. Although the information is based on data which LGT Wealth Management US Limited considers reliable, no representation or warranty (express or otherwise) is given as to the accuracy or completeness of the information contained in this Publication, and LGT Wealth Management US Limited and its employees accept no liability for the consequences of acting upon the information contained herein. Information about potential tax benefits is based on our understanding of current tax law and practice and may be subject to change. The tax treatment depends on the individual circumstances of each individual and may be subject to change in the future.
All investments involve risk and may lose value. Your capital is always at risk. Any investor should be aware that past performance is not an indication of future performance, and that the value of investments and the income derived from them may fluctuate, and they may not receive back the amount they originally invested.